Advanced Search Tools to Help You Get Exactly What You Want
Ready to find your dream home? Our advanced search tool gives you the power to filter and explore properties based on your unique preferences. Whether you're looking for specific features, price ranges, or neighborhoods, our user-friendly search will help you narrow down the perfect options with ease. Start searching today and make your home buying journey simple!
Your Go-To Resource for Real Estate Insights
Stay Ahead in Ohio’s Real Estate Market with Our Latest Blog Posts
Expert Tips, Market Trends, and Home Buying Strategies
Welcome to the MattC Group blog, where we provide you with expert advice, in-depth market analysis, and practical tips for navigating Ohio’s ever-evolving real estate landscape. Whether you’re buying, selling, or just staying informed, our blog is here to help you make the best decisions for your home and investment. Explore our latest posts and gain the knowledge you need to thrive in today’s market.
A Mortgage Rate Buydown Could Make Your Next Home More Affordable
You want to find the right home, but you also need the right monthly payment. And that can be hard when it feels like just about everything right now is putting a squeeze on your budget.
But there’s a tool that can help, and many buyers have never heard of it – it’s called a rate buydown. Here are the basics.
What Is a Rate Buydown?
When you’re borrowing money to buy a home, it usually works like this. The higher your mortgage rate, the bigger your monthly payment. And with rates where they are now, some buyers are feeling the crunch. That’s where a buydown can really come in handy.
A buydown lets you pay some money upfront to get a lower mortgage rate – and by extension a better monthly payment. Basically, it’s a way to get a lower mortgage payment without waiting for mortgage rates to fall.
There are two main types, and they work a little differently.
Temporary Buydowns: Starting Smaller
A temporary buydown lowers your rate for a specific amount of time – usually the first one to three years. When the buydown period is up, you begin making the full payment amount. The loan's official rate stays the same - you're just getting help with part of the payment in the early years.
Think of it like a gift card for your mortgage. Money goes into an escrow account at closing. Each month, part of your payment comes out of that account instead of your pocket.
Here are the most common options when it comes to temporary buydowns:
- 1-0 buydown: Your rate is 1% lower for the first year.
- 2-1 buydown: Your rate is 2% lower the first year and 1% lower the second year.
- 3-2-1 buydown: Your rate is 3% lower the first year, 2% lower the second, and 1% lower the third.
Permanent Buydowns: Lower Forever
A permanent buydown is a bit different. The big draw here is that they last for the entire loan, which could be 15 or 30 years – not just a couple of years like a temporary buydown. But normally, the monthly savings are smaller.
Here’s how this one works.
It’s paid for with points. Generally, one point equals 1% of your loan amount. And each point usually lowers your rate about a quarter of a percentage, but this differs from lender to lender. The important distinction?
- A temporary buydown gives you short-term payment relief.
- A permanent buydown can lower your payment for as long as you keep that mortgage.
Why Buydowns Are Worth Asking About Right Now
With more homes available for sale, more sellers and builders are offering incentives to attract buyers. Some are even willing to pay for your buydown.
And whether that’s advertised up front or something you ask for in negotiations, it can have a bigger impact on your bottom line than you’d think.
Take a look at this example comparing a seller-funded 2-1 buydown with a permanent buydown on a median-priced home. In this scenario, the seller would pay for the upfront buydown costs. Remember, these are estimates - your numbers will vary:
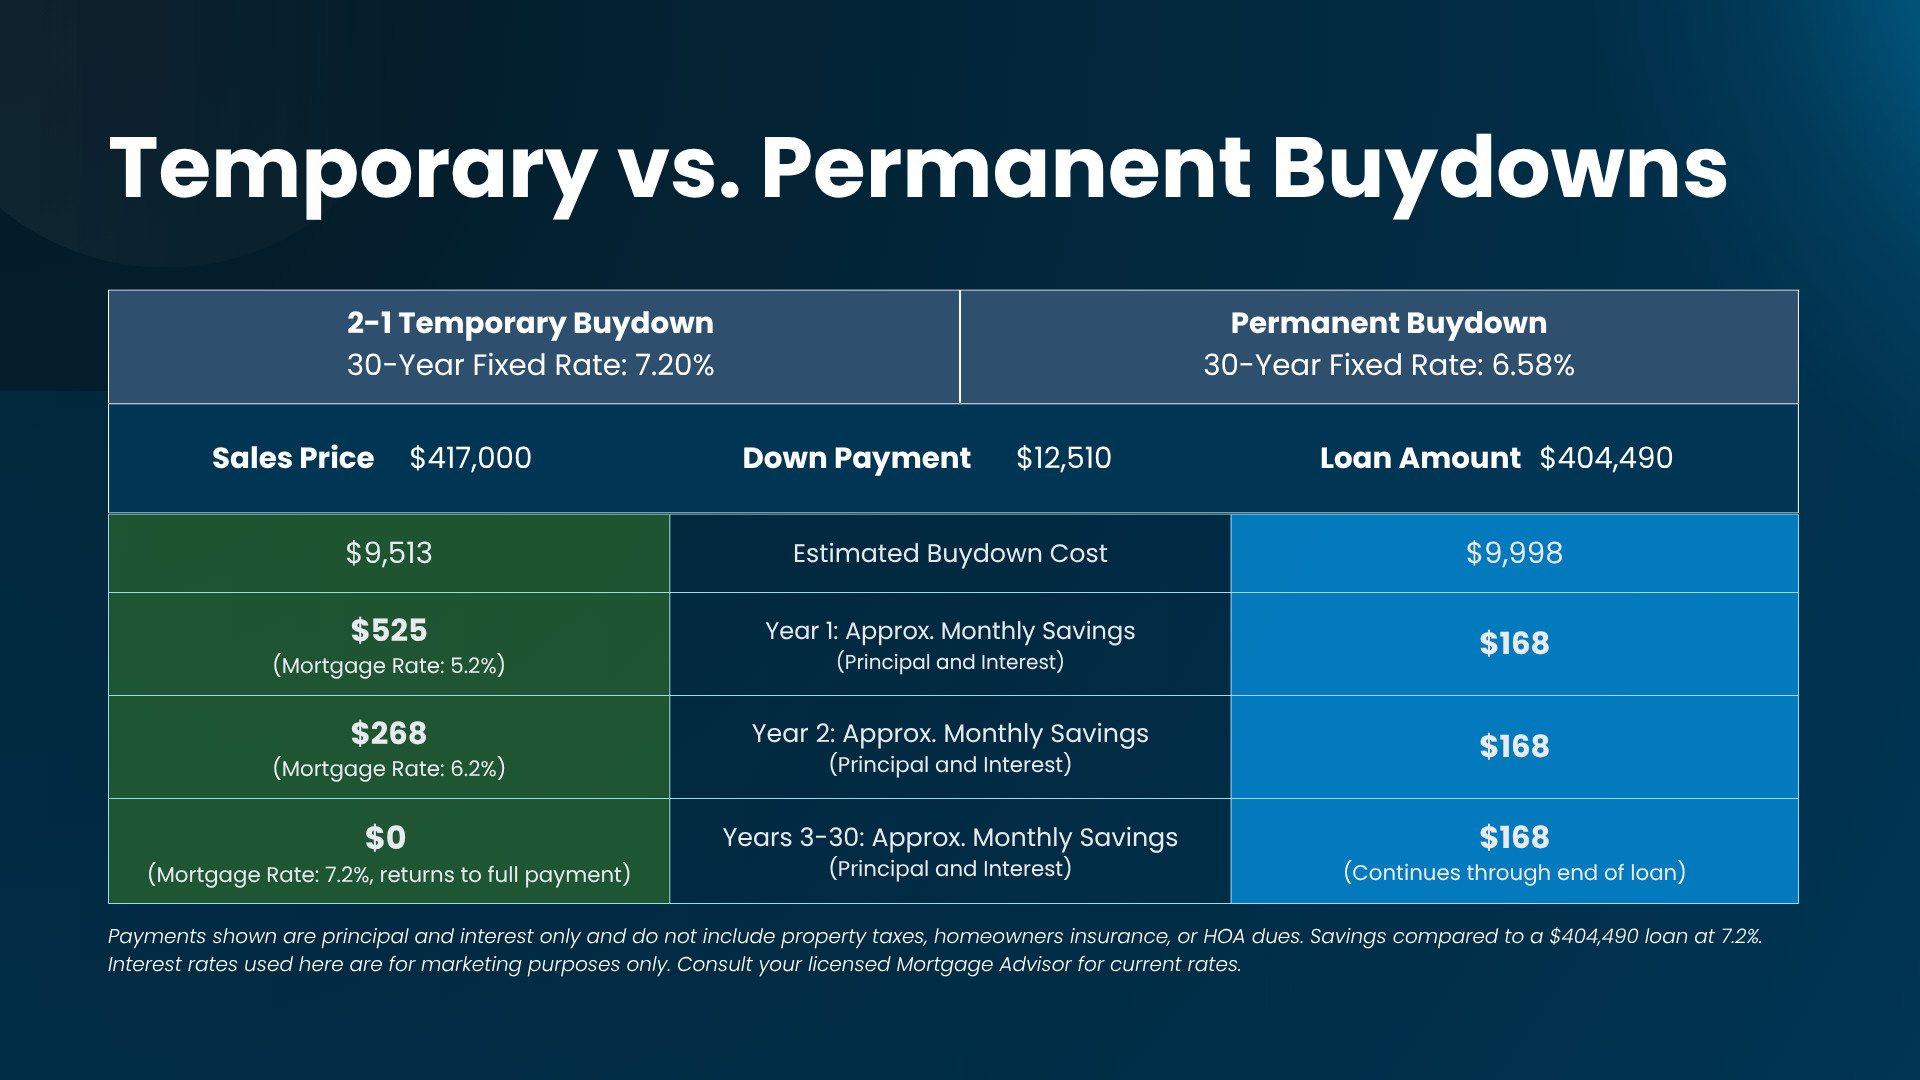
In this example, the temporary buydown provides roughly $520 in monthly payment savings during the first year, compared with about $170 a month from a permanent buydown.
That's a big difference in the short term. But there's an important tradeoff.
As mentioned before, the temporary buydown savings don't last forever. Once the buydown period ends, the full mortgage payment kicks in. That's why it's important to compare the numbers over time, not just during the first year.
How To Know if a Buydown Makes Sense for You
This is where a lender can really help you explore your options. A buydown isn't automatically the best choice for every buyer. It depends on your budget, how long you plan to stay in the home, and what you're trying to accomplish.
A temporary buydown could give you extra room in your budget during the first couple of years, when you're also managing moving expenses and settling into your new home. And if you expect your income to go up over time, this can be a good option.
On the flipside, a permanent buydown could make more sense if you plan to stay put for years and want the reassurance that the savings are sticking around until you move.
Either way, if you’re considering a buydown, the advice is simple.
- Make sure you can comfortably afford the full mortgage payment, even if you're starting with a temporary reduction.
- Factor in what it could look like if the payment goes up after the buydown period ends. You want to be sure your budget can handle it.
- Remember, lenders check whether you can afford the full payment, not just the discounted amount.
Bottom Line
If you've found a home you love but the monthly payment is giving you pause, talk to your agent about buydowns. Then, meet with your lender to see the real numbers for your situation.
A buydown could give you another way to make the numbers work, especially if a seller or builder is willing to help. Who knows it may just be the difference between "maybe someday" and "welcome home."
Your Opportunity Awaits
Ready to Take Your Real Estate Career to the Next Level?
Join a team that’s redefining success in real estate. Complete the form, and our Broker will reach out to discuss your goals and how we can help you achieve them. Let’s make it happen!
CONTACT
Need Help with The
Best Electrical
Services
Don't wait to address your electrical needs—experience the quality and reliability of Troller Electric, LLC. Our certified team specializes in exceptional commercial installations, from new construction projects for schools, retail, municipalities, restaurants, bars, multi-dwelling units, warehouses, office spaces, and strip malls. We also provide top-tier residential services. Call us now to schedule same-day service or to speak with one of our experts.
With 24/7 support, competitive pricing, and a one-year warranty on all services, we ensure your complete satisfaction. Contact us today and discover why Troller Electric is the preferred choice for countless satisfied customers.
For Emergency
See why so many home service companies
want to work with us!
I seen the company grow by over $5M
“The Merdian Company is based in East Lansing, MI and provide Plumbing, HVAC, Remodeling & Electrical services.”
Hear From Craig Phillipich
Owner of The Medidian Company.
MattC Group serves Cincinnati, Dayton, and Columbus with expert real estate services, fast results, and clear communication every step of the way.
Follow us!


Quick Links
Service Areas