Advanced Search Tools to Help You Get Exactly What You Want
Ready to find your dream home? Our advanced search tool gives you the power to filter and explore properties based on your unique preferences. Whether you're looking for specific features, price ranges, or neighborhoods, our user-friendly search will help you narrow down the perfect options with ease. Start searching today and make your home buying journey simple!
Your Go-To Resource for Real Estate Insights
Stay Ahead in Ohio’s Real Estate Market with Our Latest Blog Posts
Expert Tips, Market Trends, and Home Buying Strategies
Welcome to the MattC Group blog, where we provide you with expert advice, in-depth market analysis, and practical tips for navigating Ohio’s ever-evolving real estate landscape. Whether you’re buying, selling, or just staying informed, our blog is here to help you make the best decisions for your home and investment. Explore our latest posts and gain the knowledge you need to thrive in today’s market.
Why More Buyers Are Turning To Adjustable-Rate Mortgages Today
When mortgage rates climb, buying a home can start to feel like trying to hit a moving target. Every jump in rates makes monthly payments bigger, and that pushes a lot of buyers to look for another way in.
More and more of them are finding it in the adjustable-rate mortgage, or ARM.
The ARM Option
Here’s how an ARM differs from a more traditional mortgage. With a regular fixed-rate mortgage, your rate stays the same for your whole loan. But with an ARM, your rate is locked for the first few years, then it can move up or down based on market conditions.
Some people don’t like that level of uncertainty – and that’s okay. But others are drawn to this option specifically because there’s usually a lower rate to start when you opt for an ARM. And in an affordability-strapped market, that’s going to gain popularity.
Bankrate recently found that, in September, rates for ARM products were over a full percentage point lower than a regular fixed-rate loan. Depending on the ARM product, that can make a difference of $150-300 in the monthly payment on a median-priced home.
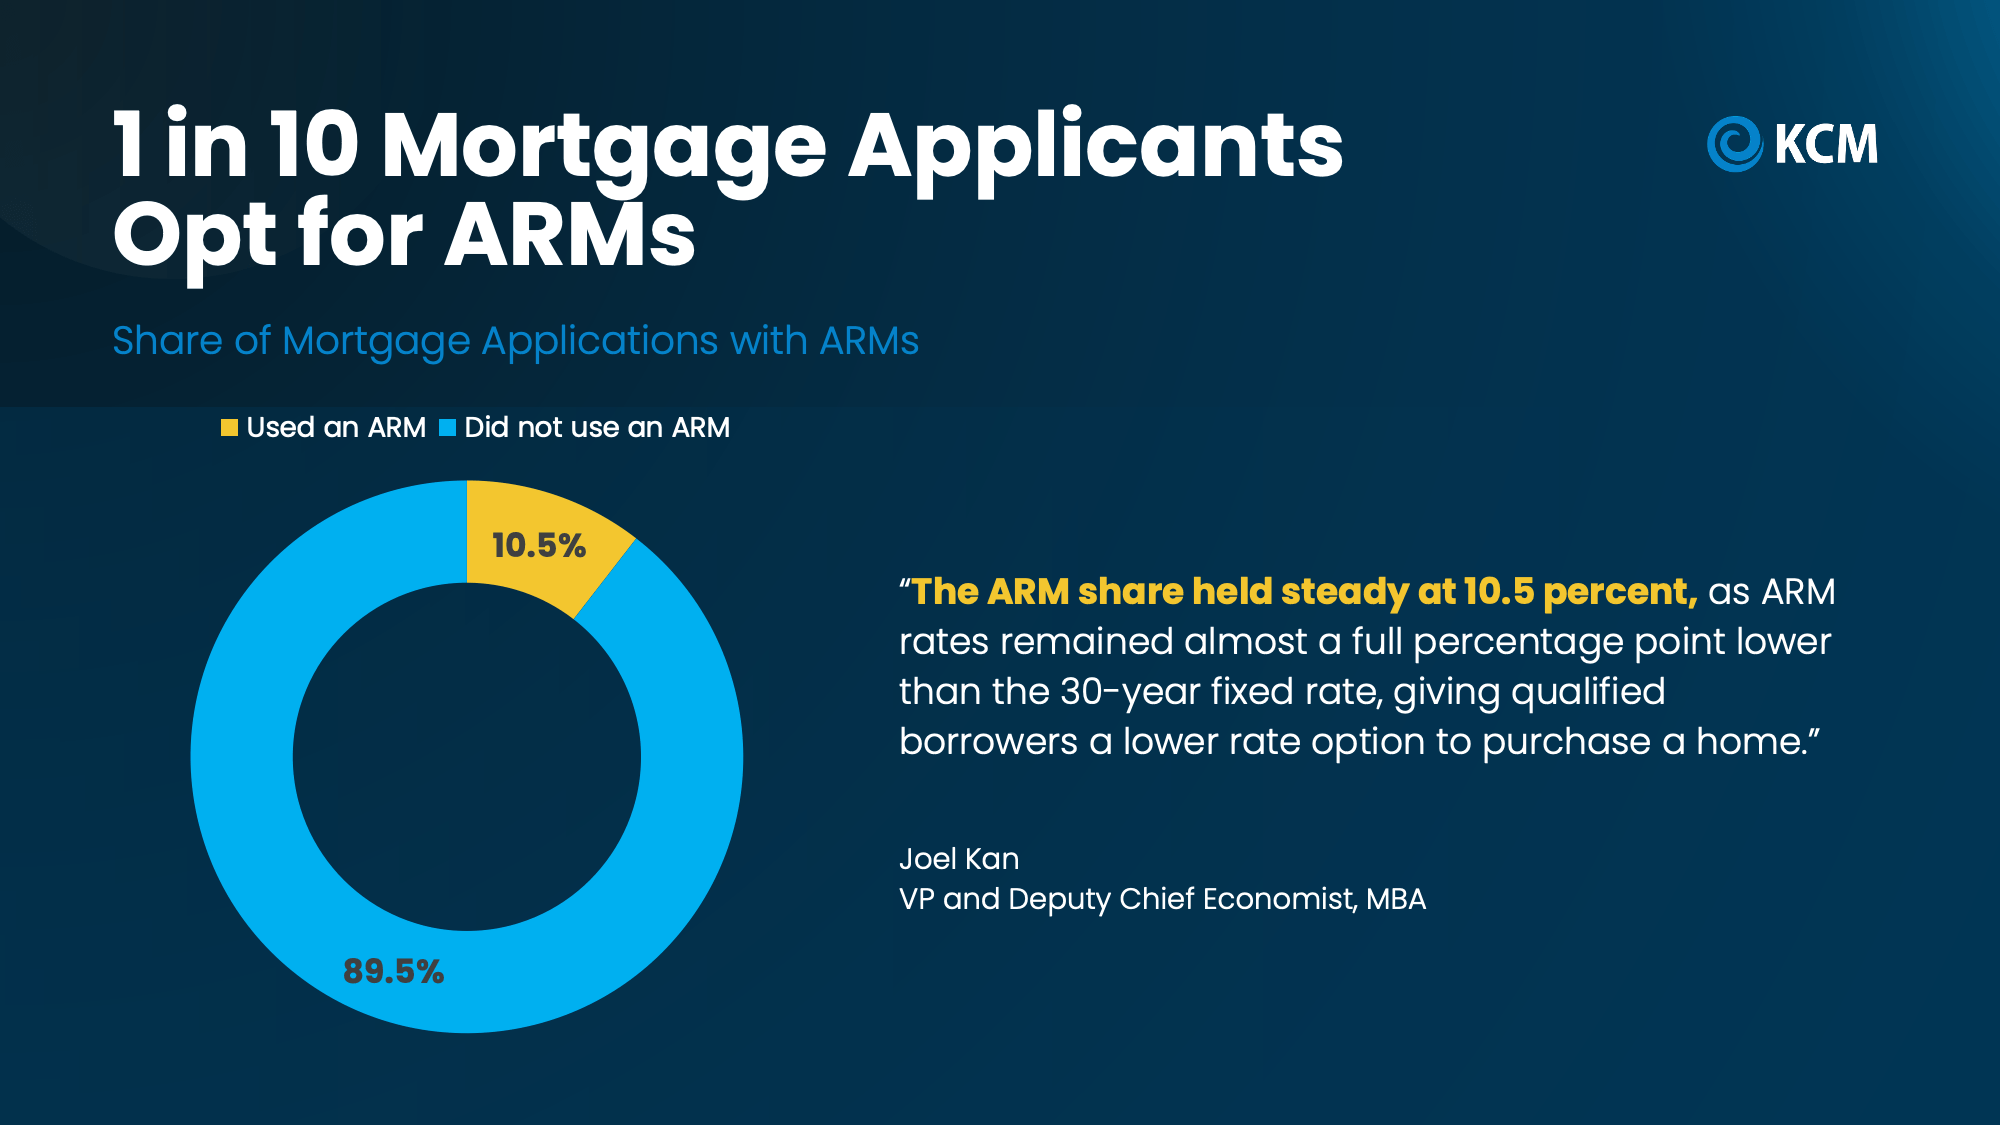
And for some buyers, that’s enough to turn “not right now” into “let’s do this.” You can see it in the numbers. Data from the Mortgage Bankers Association (MBA) shows that, in October, roughly 1 in 10 people applying for a mortgage chose an ARM (see graph below):
If you think you may want to consider this yourself, here’s what you need to know about how it works.
The 5/1 ARM
An ARM is like a phone or cable plan that has an introductory deal for new customers. You start out at a lower price, and then it adjusts after a specified amount of time. A popular loan is the 5/1 ARM.
The “5” means your introductory rate is locked for the first five years, and the “1” means that the rate can change every year after that. The rate change is called the “reset.” And here’s the really important part.
When your rate resets, your mortgage payment could go up or down. The good news is that most ARMs have caps, which are limits on how much your rate can rise each year and over the life of the loan. But either way, you have to be ready.
The Upsides and Potential Downsides
To see if this type of loan may be right for you, here are some things to think about and discuss with your loan officer:
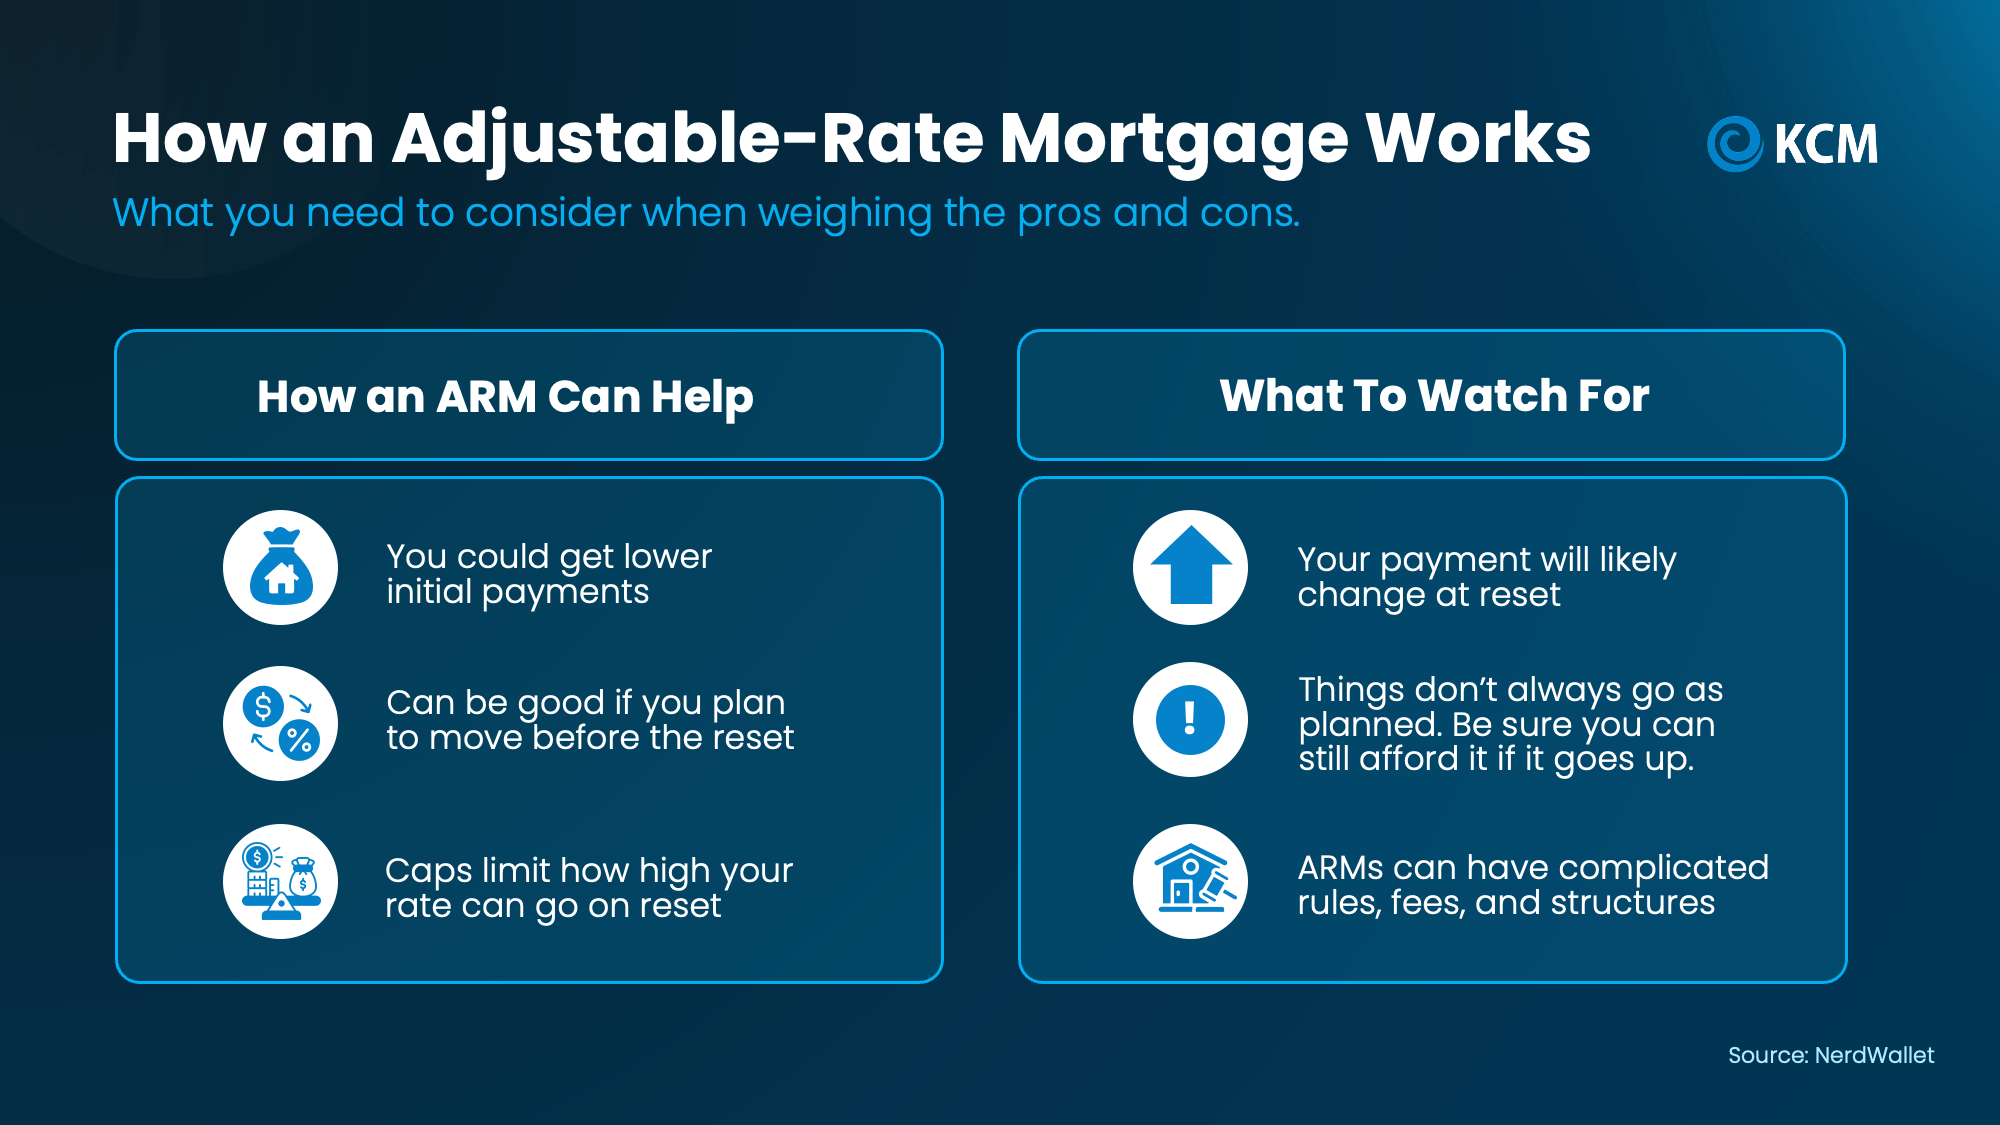
Before you decide, ask your lender to work up the numbers and walk you through the different potential scenarios you could run into with an ARM. That way, you go in with your eyes open.
Be Ready for the Reset
And, if you do go with an adjustable-rate mortgage, just know that you'll have choices when the reset time arrives. You could:
- Do nothing and keep your loan in place if the new payment still fits your budget.
- Refinance into a fixed-rate loan with a payment that never changes.
- Refinance into another ARM with a new lower rate locked for a specified timeframe.
- Sell your home.
- Talk to the loan servicer about assistance or modification.
Remember, a refinance is a brand-new loan that you'll have to qualify for – even if it's on a home you already own. So, keep tabs on your credit and debt levels and ask your loan officer how major financial moves like job changes and major purchases will affect your mortgage readiness. It's important to keep your credit and finances in “mortgage shape.”
Today’s ARMs Aren’t Like 2008
One more quick note. ARMs got a bad name after the financial crisis of 2008. Back then, there were some risky loans with small starting payments that later shot way up. Others let people borrow without proving how much money they earned.
But now, there are new laws to protect both borrowers and lenders. The biggest change is the Ability-to-Repay Rule, which says that before a lender makes a home loan, it has to check real paperwork (like pay stubs, W-2 forms, and tax returns) to make sure you can afford it. The lender also has to look at what your payment could be after the reset, not just the low starting payment.
So, you don’t have to worry that today’s ARMs are the same as the ones we saw back during the crash.
Bottom Line
Today's market has more options than many people realize. Finding the right one could be as simple as getting more information about tools like ARMs. A trusted lender can run the numbers with you, walk you through the what-ifs, and help you explore the possibilities.
Is an ARM a good option for you? Talk to a loan officer to find out.
Your Opportunity Awaits
Ready to Take Your Real Estate Career to the Next Level?
Join a team that’s redefining success in real estate. Complete the form, and our Broker will reach out to discuss your goals and how we can help you achieve them. Let’s make it happen!
CONTACT
Need Help with The
Best Electrical
Services
Don't wait to address your electrical needs—experience the quality and reliability of Troller Electric, LLC. Our certified team specializes in exceptional commercial installations, from new construction projects for schools, retail, municipalities, restaurants, bars, multi-dwelling units, warehouses, office spaces, and strip malls. We also provide top-tier residential services. Call us now to schedule same-day service or to speak with one of our experts.
With 24/7 support, competitive pricing, and a one-year warranty on all services, we ensure your complete satisfaction. Contact us today and discover why Troller Electric is the preferred choice for countless satisfied customers.
For Emergency
See why so many home service companies
want to work with us!
I seen the company grow by over $5M
“The Merdian Company is based in East Lansing, MI and provide Plumbing, HVAC, Remodeling & Electrical services.”
Hear From Craig Phillipich
Owner of The Medidian Company.
MattC Group serves Cincinnati, Dayton, and Columbus with expert real estate services, fast results, and clear communication every step of the way.
Follow us!


Quick Links
Service Areas